Is SafetyWing Worth It in Asia? We Used It This Summer: Pros and Cons
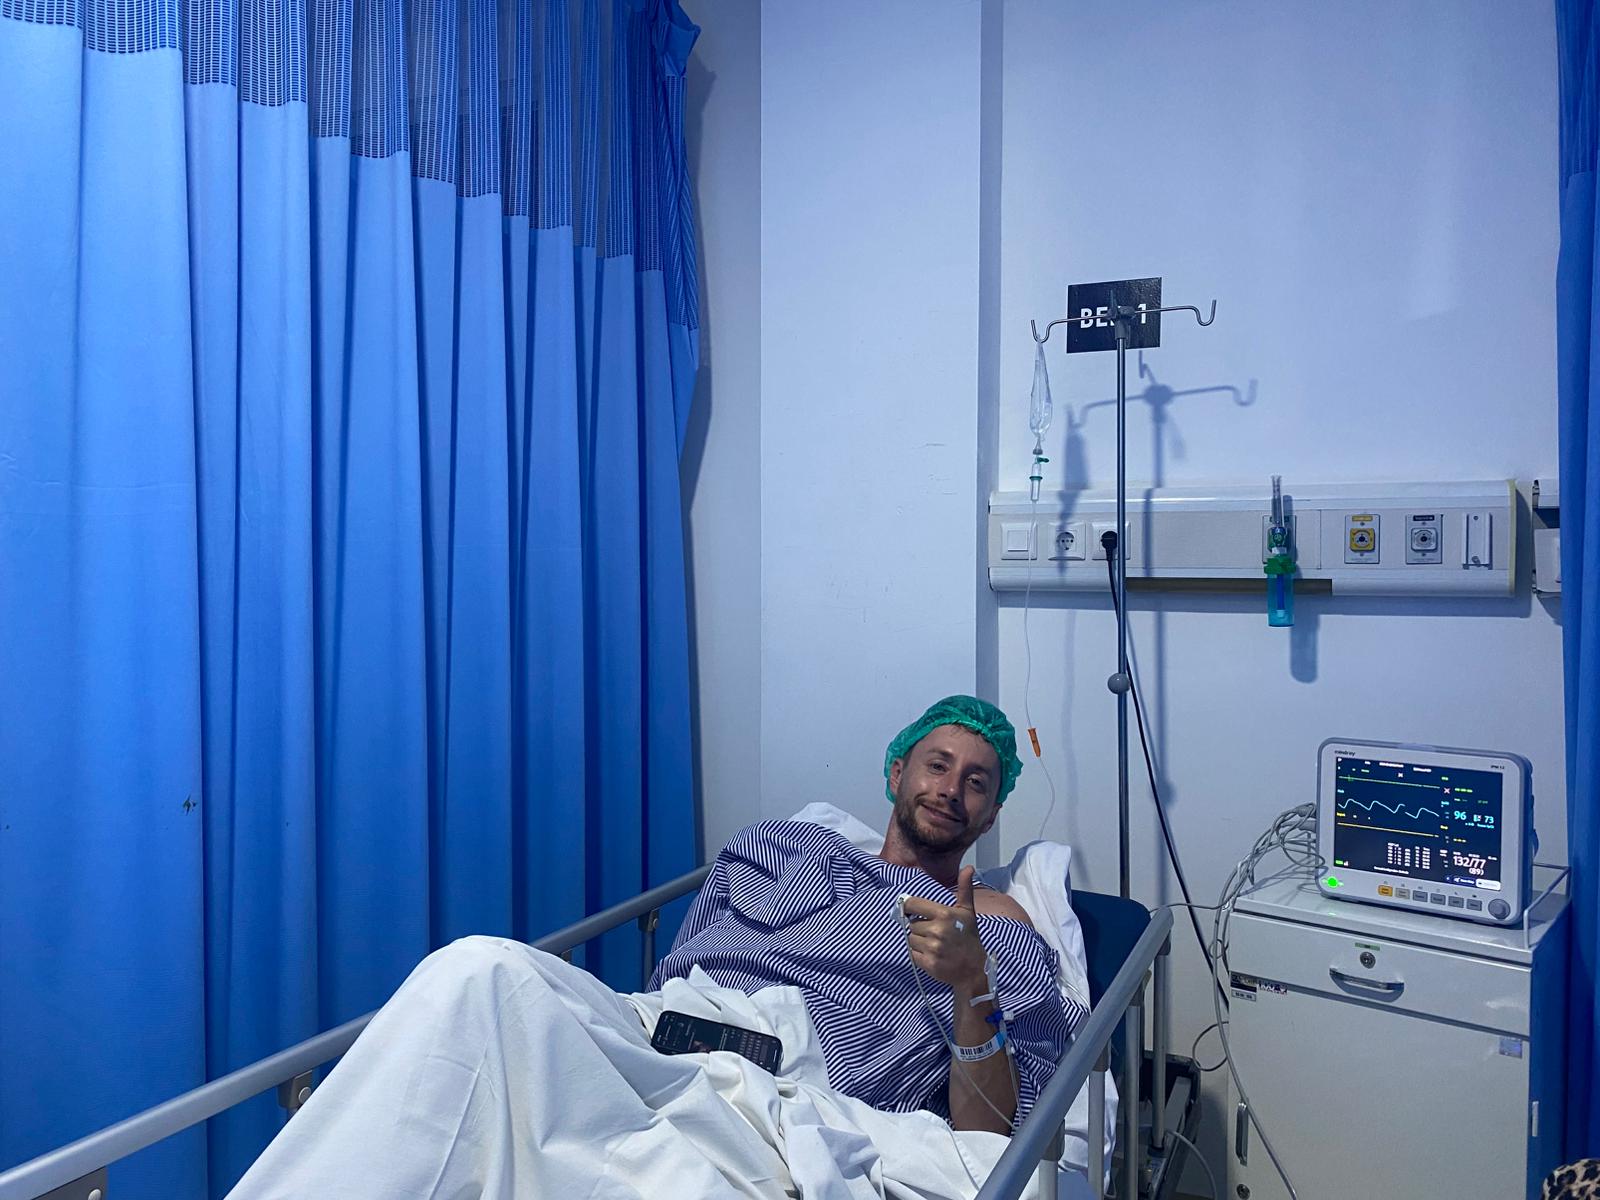
Mataram, Lombok, with a dislocated shoulder. My credit card’s insurance paid that bill, not SafetyWing, and it’s the reason I now scrutinize every insurance policy when I travel for more than 4 weeks
I dislocated my shoulder in Lombok playing beach volleyball. What came after was worse than the fall itself: a hospital in Mataram where they treated me badly, hours of waiting and a bill of around $3,000.
My credit card’s insurance paid it. And that day I learned something you only really learn when you end up in a hospital 12,000 km from home: you need travel medical insurance on every trip, no exceptions.
So when my partner and I planned her four-week trip around Asia this summer, we didn’t want to gamble. A stomach bug, a bite from some strange mosquito or a fall means thousands of dollars in hospital bills, and all your savings can disappear into one emergency surgery.
She went with SafetyWing, a travel medical insurance plan built for nomads: $62.72 for four weeks, from August 5 to September 1.
When she told me about it, I started digging, and I liked what I found. Now I’m about to spend more than 90 days traveling and working around Asia (November, December and January), and my credit card’s insurance doesn’t cover trips that long: on premium cards in Spain, the limit is usually 30 days in a row.
So this time we’ve both bought it, her for the second time and me for the first.
I’ll say it up front, because it’s the first thing you’d want to know: we haven’t had to use it. I can’t tell you how they handle a claim, because we haven’t made one. What I can tell you is what it costs, what it covers, what it doesn’t, and what to do if something happens to you, straight from the policy and not from the ads.
One warning before you head to their site: with my code DESCUBRIENDO you get 8 free weeks of the electronics theft add-on, but the code goes in before you create your account, not at checkout. I’ll show you where, because it’s hidden.
SafetyWing Essential in 30 seconds
| What you want to know | The short answer |
|---|---|
| How much does it cost? | $62.72 every 4 weeks if you’re 18 to 39, about $2.24 a day |
| Is there a discount code? | DESCUBRIENDO: 8 free weeks of the electronics theft add-on, if you enter it before creating your account |
| What does it cover? | Hospital and surgery up to $250,000, evacuation, luggage, delays and canceled accommodation |
| What doesn’t it cover? | Pre-existing conditions, mental health, cancer and, without add-ons, the United States and electronics theft |
| Do they pay up front? | With the 4-week plan, generally not: you pay and they reimburse you, unless you’re admitted, in which case they can pay the hospital themselves. The annual plan comes with a prepaid card loaded with $150 for minor doctor visits, and Complete with $500 |
| Essential or Complete? | For a trip of a few weeks or a few months, Essential. Complete is health insurance for people who live abroad |
What it costs: about $2 a day
The Essential plan costs $62.72 every four weeks if you’re between 18 and 39. Broken down per day, which is how it really makes sense, that’s $2.24: less than a mango shake at any stall in Koh Samui.
It works like a subscription: they charge you every four weeks, and you cancel it when you get home. You don’t need to know in advance how long the trip will last, which is exactly your situation when you fly to Asia on a one-way ticket.
If you already know your return date, you can also buy specific dates and pay for them in one go, with a minimum of 5 days, with the “Pay in full for specific dates” option.
And if you’re going away for a full year, you can pay for 364 days at once. That works out to $56.45 every four weeks, 10% less. You also get a prepaid debit card loaded with $150 for minor doctor visits, and in your home country it covers you for up to 90 days in a row per visit, with a maximum of 179 a year.
This is the checkout screen for the plan I’m about to buy, the four-week one:
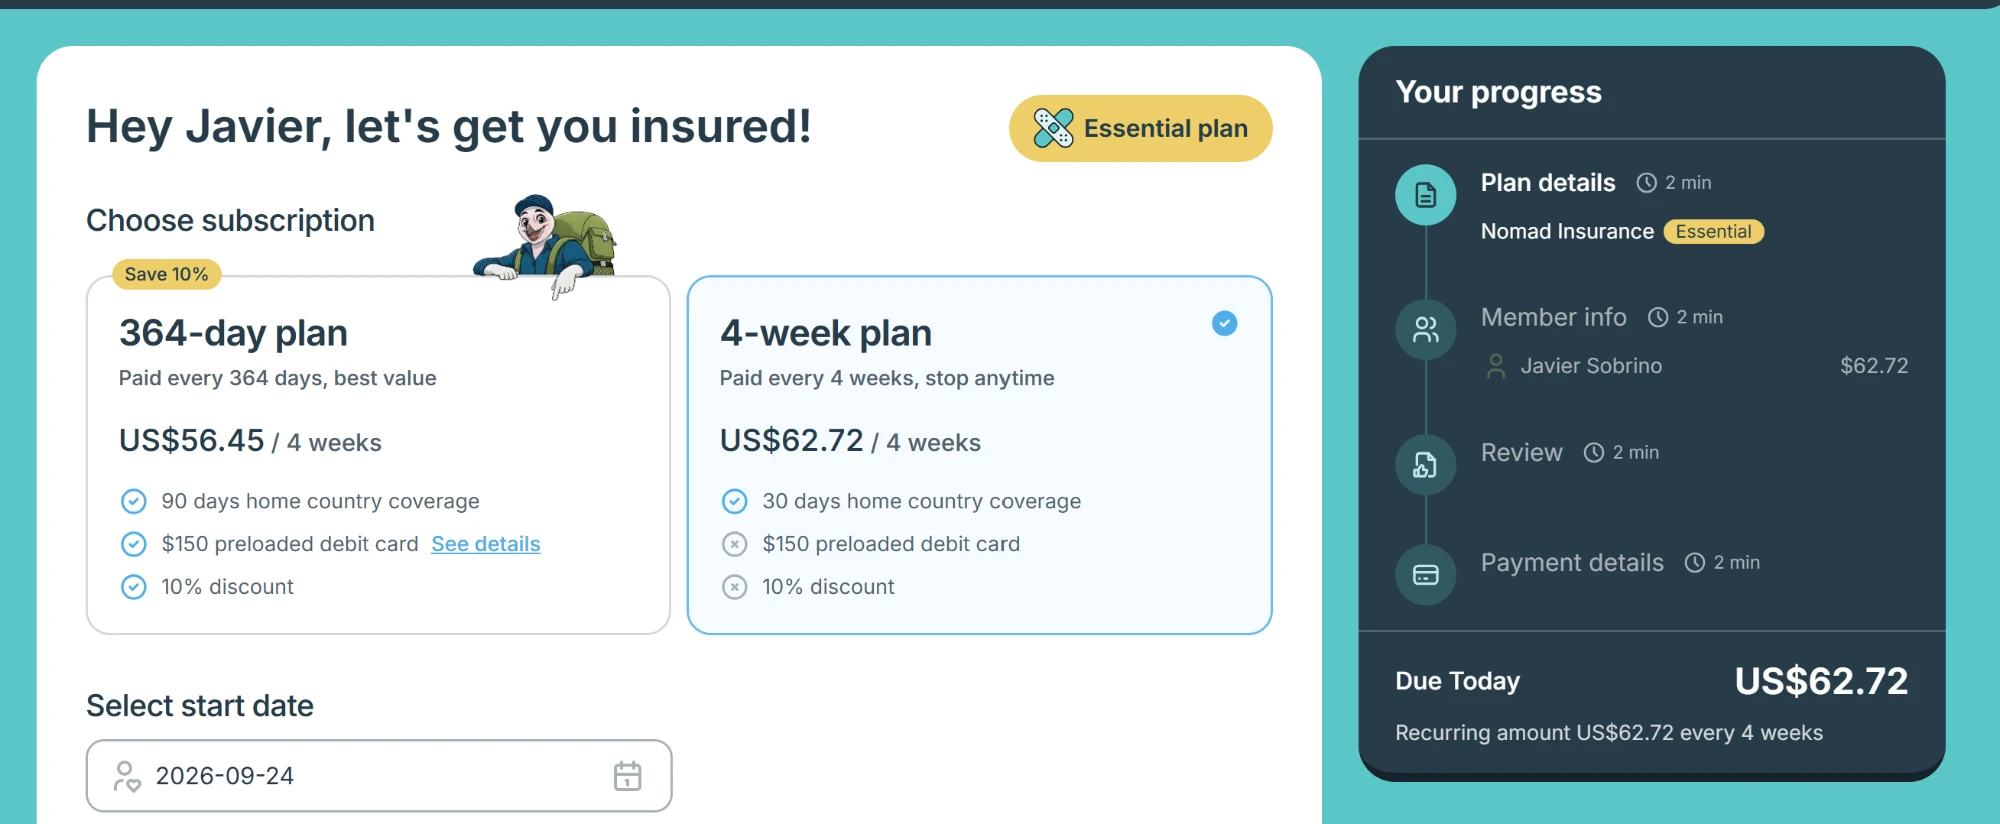
My Essential sign-up: $62.72 every 4 weeks, and I can stop it whenever I want
And this is my partner’s policy from this summer. She bought it on July 31, before leaving, for four weeks with no add-ons:
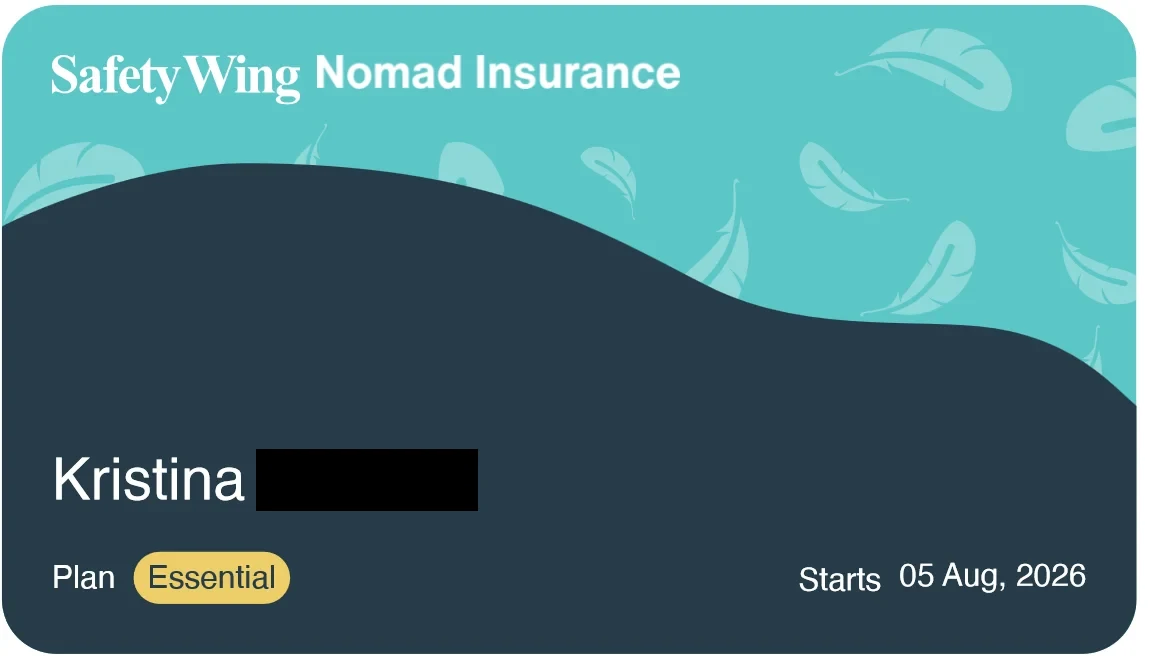
Her Essential policy card. I’ve hidden her last name and the policy number
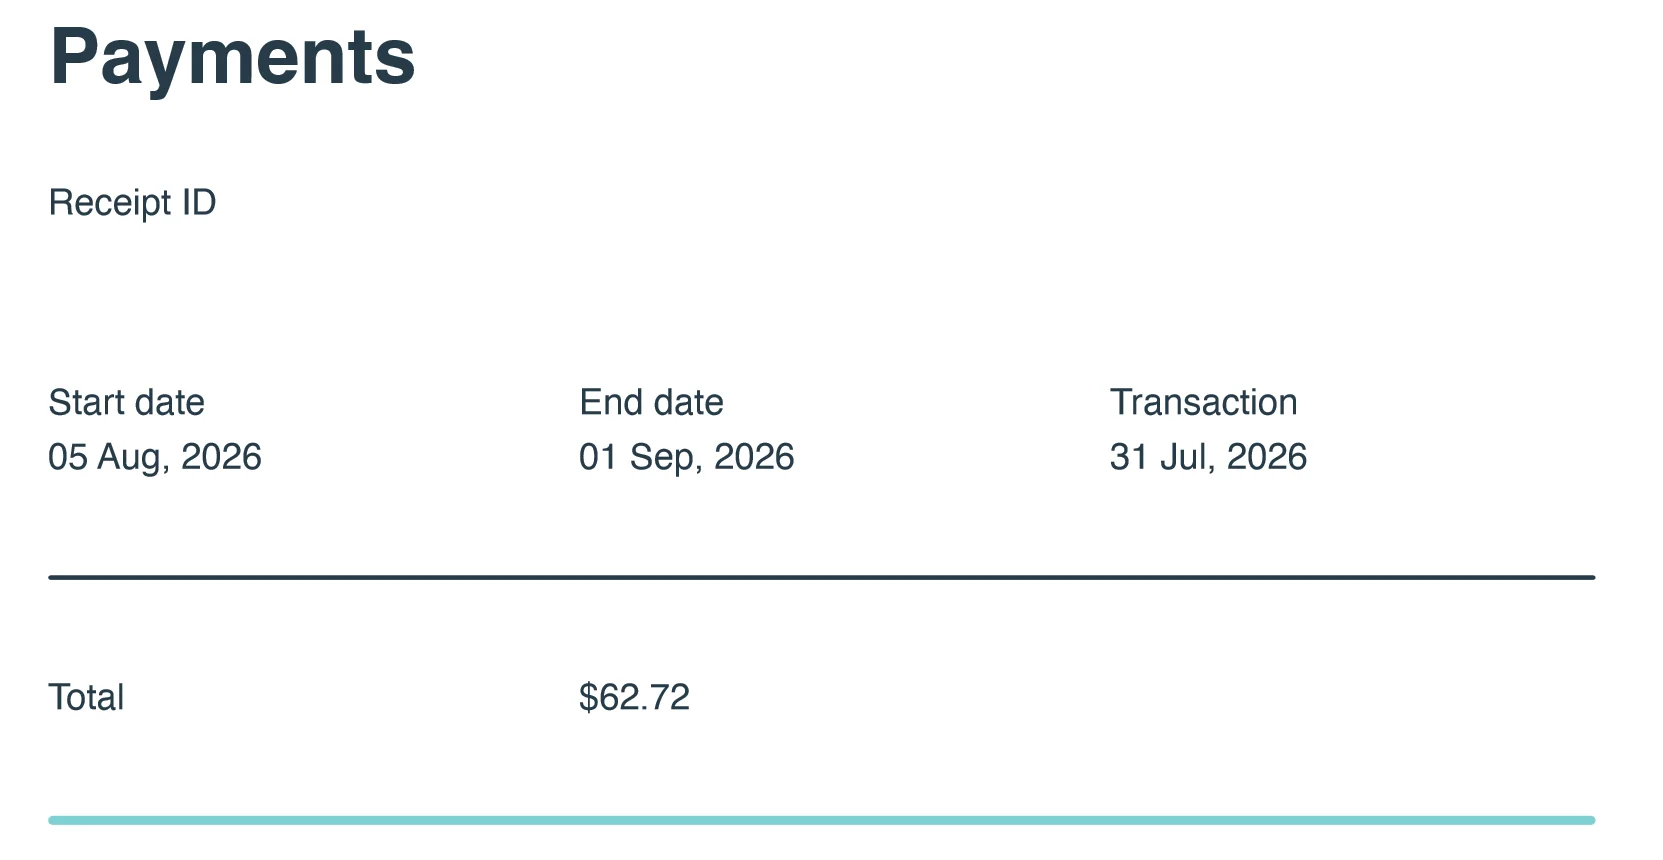
The receipt: August 5 to September 1, $62.72
From age 40, the price goes up by age bracket, and from 70 on, you can no longer buy it. The quickest way to find out is to type your age into their calculator.
| My partner, this summer | Both of us, this winter | |
|---|---|---|
| Plan | Essential | Essential |
| Dates | August 5 to September 1 | November, December and January |
| Add-ons | None | Still deciding |
| Payment | $62.72 every 4 weeks | $62.72 every 4 weeks |
| Approximate total | $62.72 | about $200 each |
What travel medical insurance is really for in Asia
Travel around Asia and you’ll end up eating at food markets, street stalls and kiosks. And one question will follow you from plate to plate: is this going to make me sick?
If it does, it makes no difference whether you have travel medical insurance or not: you’ll spend one day with a fever and three eating bland food. What changes is your peace of mind.
With it, if the fever climbs a little, you’re at the hospital in 20 minutes and you don’t care if the visit costs $300: you pay, keep the medical report and the invoice, and they pay you back.
And that’s before we get to a dislocated shoulder or an infected tooth. In those cases, without travel medical insurance, get your wallet ready.
These aren’t textbook examples: ending up in the hospital while traveling in Asia is more common than you think. It has happened to me and to friends, and here are the two cases I have photos of.
My shoulder, twice
In 2023 I dislocated my shoulder swimming in Thailand. They popped it back in at a basic clinic and the whole episode came to about $575.
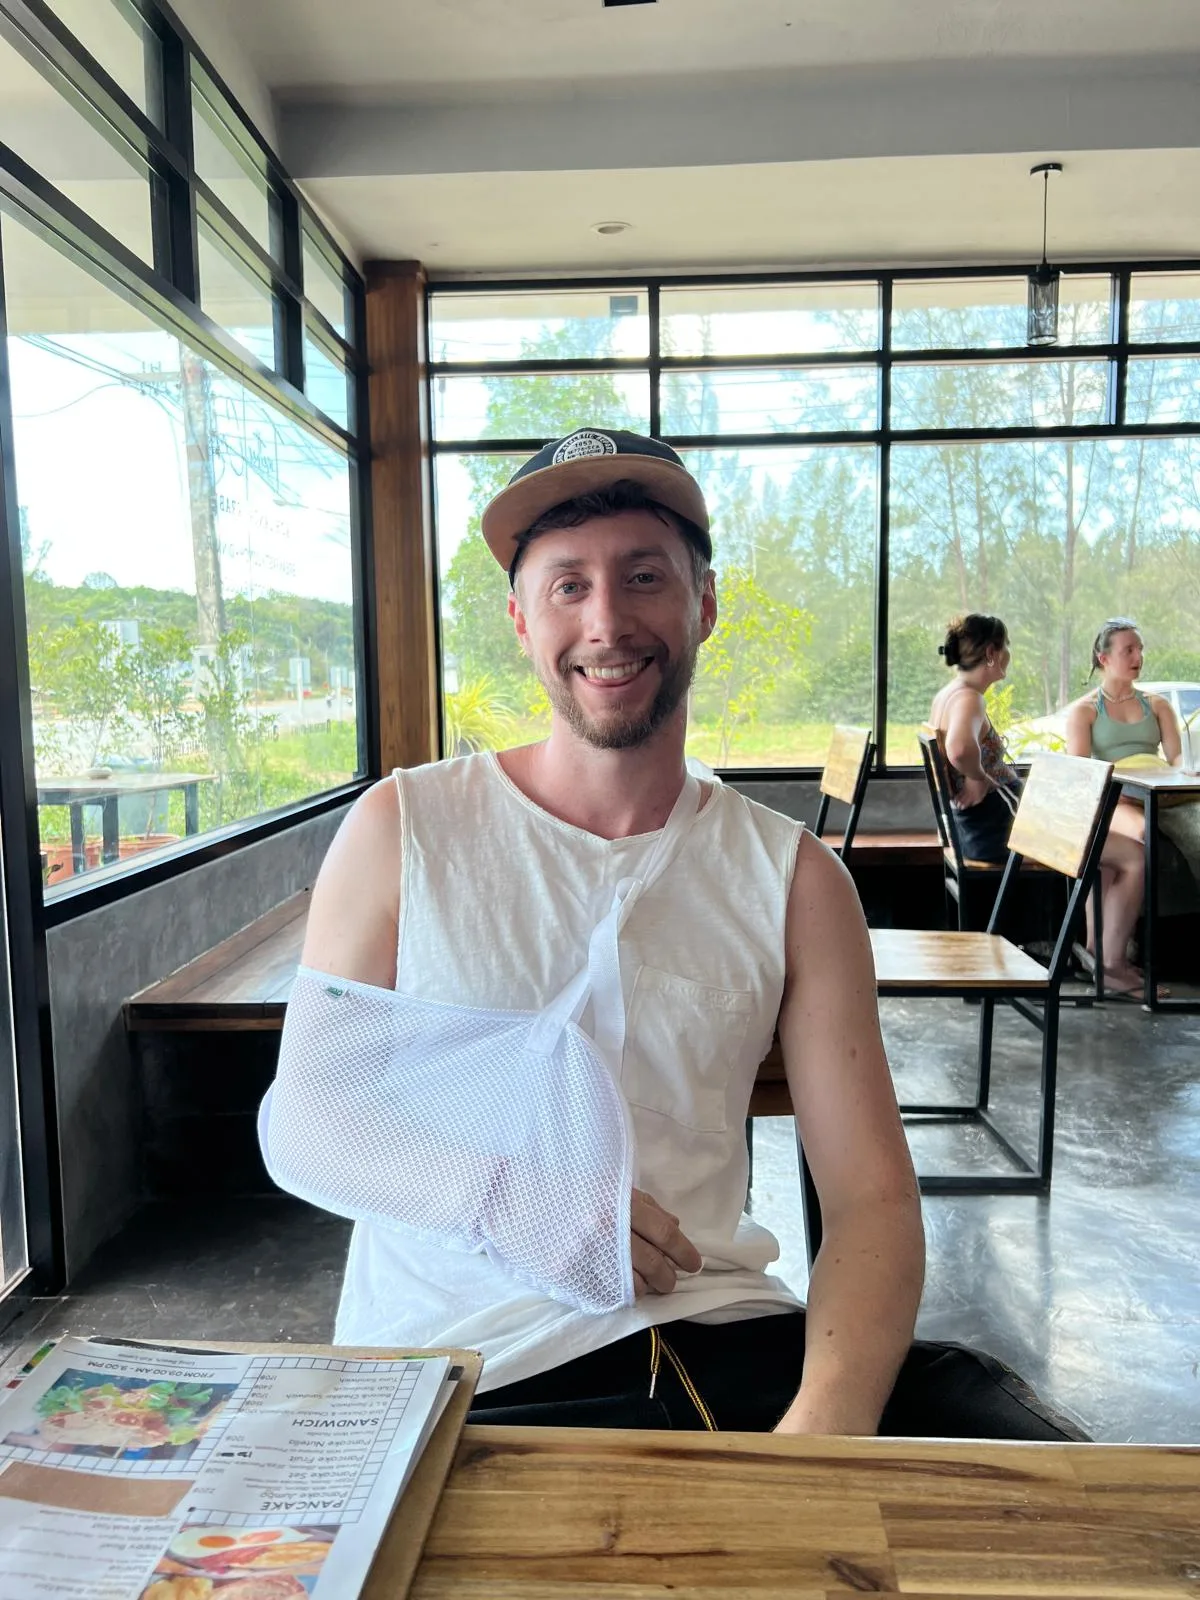
Thailand, 2023: shoulder back in place and arm in a sling. I’m smiling because the worst was over
It was never quite right after that, and in 2025 it popped out again playing volleyball in Lombok. Getting it back in turned into a circus there, with an anesthesiologist and a surgeon, and then came the bill, around $3,000.
These days I don’t swim and I avoid sudden movements. I need surgery, but I’m not keen on spending several months with my shoulder immobilized, so I keep putting it off and try to be very careful.
Now the honest part: for SafetyWing, an injury counts as pre-existing if, in the 180 days before the policy starts, a doctor saw you for it, treatment was recommended, you took medication or you had symptoms.
If it counts as pre-existing, they don’t cover it in general, but they do cover the emergency: if it pops out again, I could be covered as long as I see a doctor within the first 24 hours and it doesn’t happen in the first 28 days of the policy.
This matters because not every policy covers it, and you can get a nasty surprise when you go to claim thousands of dollars for your hospital visit.
What it wouldn’t cover is the surgery I still need, because that’s not an emergency. And if they decide my shoulder is a condition that gets worse over time, the emergency wouldn’t be covered either: they judge that case by case. If you have an old injury or illness, ask in their chat before you buy.
Victor’s knee
Victor, my business partner and co-founder of Discovering Stays, was walking back at night along an unlit path on a Thai island (Koh Lanta, which I highly recommend, by the way). He was in flip-flops, one got caught on a rock and he split his knee open.
It was a filthy dirt path, so we went to a clinic to get the wound properly cleaned and get a special ointment. The treatment cost about $520.
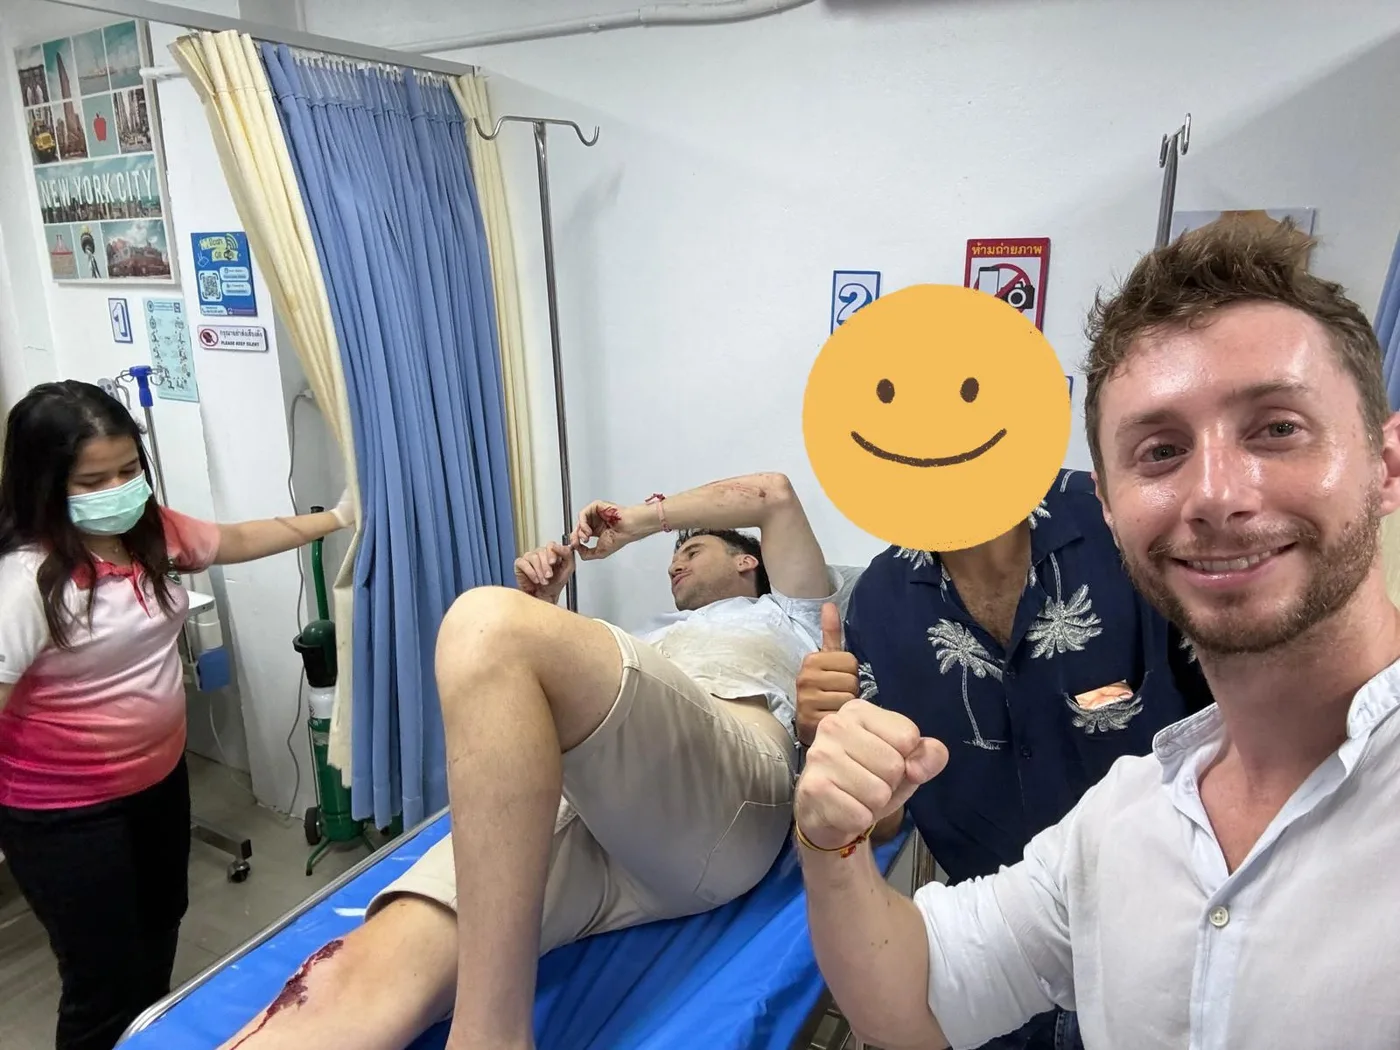
Victor on the stretcher with his knee open, and me cheering him on. The one with the emoji asked not to be shown
None of the three scares was serious. Even so, together they cost more than $4,000 in clinics and hospitals.
What Essential covers that matters in Asia
I’m not going to paste the whole policy here. This is what I look at with a long trip through Thailand, Vietnam or Indonesia in mind:
- Doctors and hospitals up to $250,000 for new illnesses or accidents: admissions, surgery, medication, tests and ambulance.
- Evacuation to a better-equipped hospital, up to $100,000 over your whole lifetime as a policyholder. From Lombok, that would have meant flying to Bali. And on an island with no cars like Koh Phi Phi, it means leaving by boat.
- Injuries from recreational sports, with the same medical cover. My first shoulder dislocation, the one in Thailand, would have been covered here.
- Lost checked luggage: up to $500 per item and $3,000 in total.
- Delays: $60 if your transport is 3 to 8 hours late, and $150 if it’s more than 8 and you have to spend the night somewhere.
- Accommodation that gets canceled or that you can’t reach, a stolen passport or wallet, and evacuation due to civil unrest up to $10,000.
- Up to 30 days of medical cover in your home country per visit, as long as your insurance has been active for 90 days or more. With the annual plan, up to 90 days in a row. Handy if you fly home for Christmas.
And the thing that decides it for me: you can buy it when you’re already traveling. If you’re abroad, coverage starts as soon as you get the email with your policy. If you’re still at home, it starts when you cross the border.
That changes everything if you leave on a one-way ticket and decide to stay longer as you go. Some travel medical insurance plans won’t let you buy once you’ve left, and make you choose how long you’ll be away before you board the plane.
Essential or Complete: which one makes sense for you
SafetyWing sells two plans, and they’re less alike than they seem. Essential is travel medical insurance for the unexpected; Complete is full health insurance with travel protections on top.
| Essential, 4 weeks | Essential, 1 year | Complete | |
|---|---|---|---|
| Price (ages 18 to 39) | $62.72 every 4 weeks | $56.45 every 4 weeks, in a single payment | $177.50 a month |
| Per day | $2.24 | $2.02 | about $5.80 |
| Medical limit | $250,000 | $250,000 | $1,500,000 a year |
| Prepaid card for doctor visits | No | $150 | $500 |
| Routine care and checkups | No | No | Yes |
| Mental health | No | No | 10 sessions a year |
| Cancer | No | No | Yes |
| Maternity | Complications only | Complications only | Up to $2,500, after 10 months |
| Minimum commitment | None | The year, paid in one go | 12 months |
| In your home country | 30 days per visit, after 90 days of coverage or more | 90 days in a row per visit, 179 a year | No restrictions |
For a trip of a few weeks or a few months, Essential is the one that makes sense to me: it covers what can happen to you on the road, which is exactly what you don’t see coming.
Complete is a different product. It’s designed for people who already live abroad and need a family doctor, checkups or therapy wherever they are. With a 12-month commitment, it isn’t meant for a long vacation, and at almost three times the price it doesn’t pay off for me either, since I already have Spain’s public health system back home.
What it doesn’t cover, and where it falls short
This is the part the ads don’t show you, and the part I care about most. I’ve read their whole description of coverage, and this is what you need to know before you pay:
- With the 4-week plan, you pay up front. The policy itself says so: it’s “pay and claim” travel medical insurance. You see the doctor, you pay, and then you ask for a refund. Only for hospital admissions can they pay the hospital directly, and you have to tell them before you’re discharged. With the annual plan and with Complete you get a prepaid card for minor doctor visits, loaded with $150 and $500 respectively.
- Pre-existing conditions. Not covered, except for a one-off emergency. For them, pre-existing means any injury or illness for which, in the 180 days before the policy starts, a doctor saw you or recommended treatment, you were prescribed something or you had symptoms bad enough to see a doctor, plus any symptom in the 10 days before you bought it. And watch out for this one: every time you buy a new plan with a new start date, anything you had up to that day becomes pre-existing.
- Motorbikes, only with a license and a helmet. If you crash without a valid license for that bike, you’re not covered. In Southeast Asia, where it seems like everyone rents a motorbike without a license, this is the most important line in the whole policy. By the way, in Vietnam small, low-powered, speed-limited electric motorbikes can be ridden legally without a license. That’s the kind I use, and Is Vietnam Safe? has the exact figures.
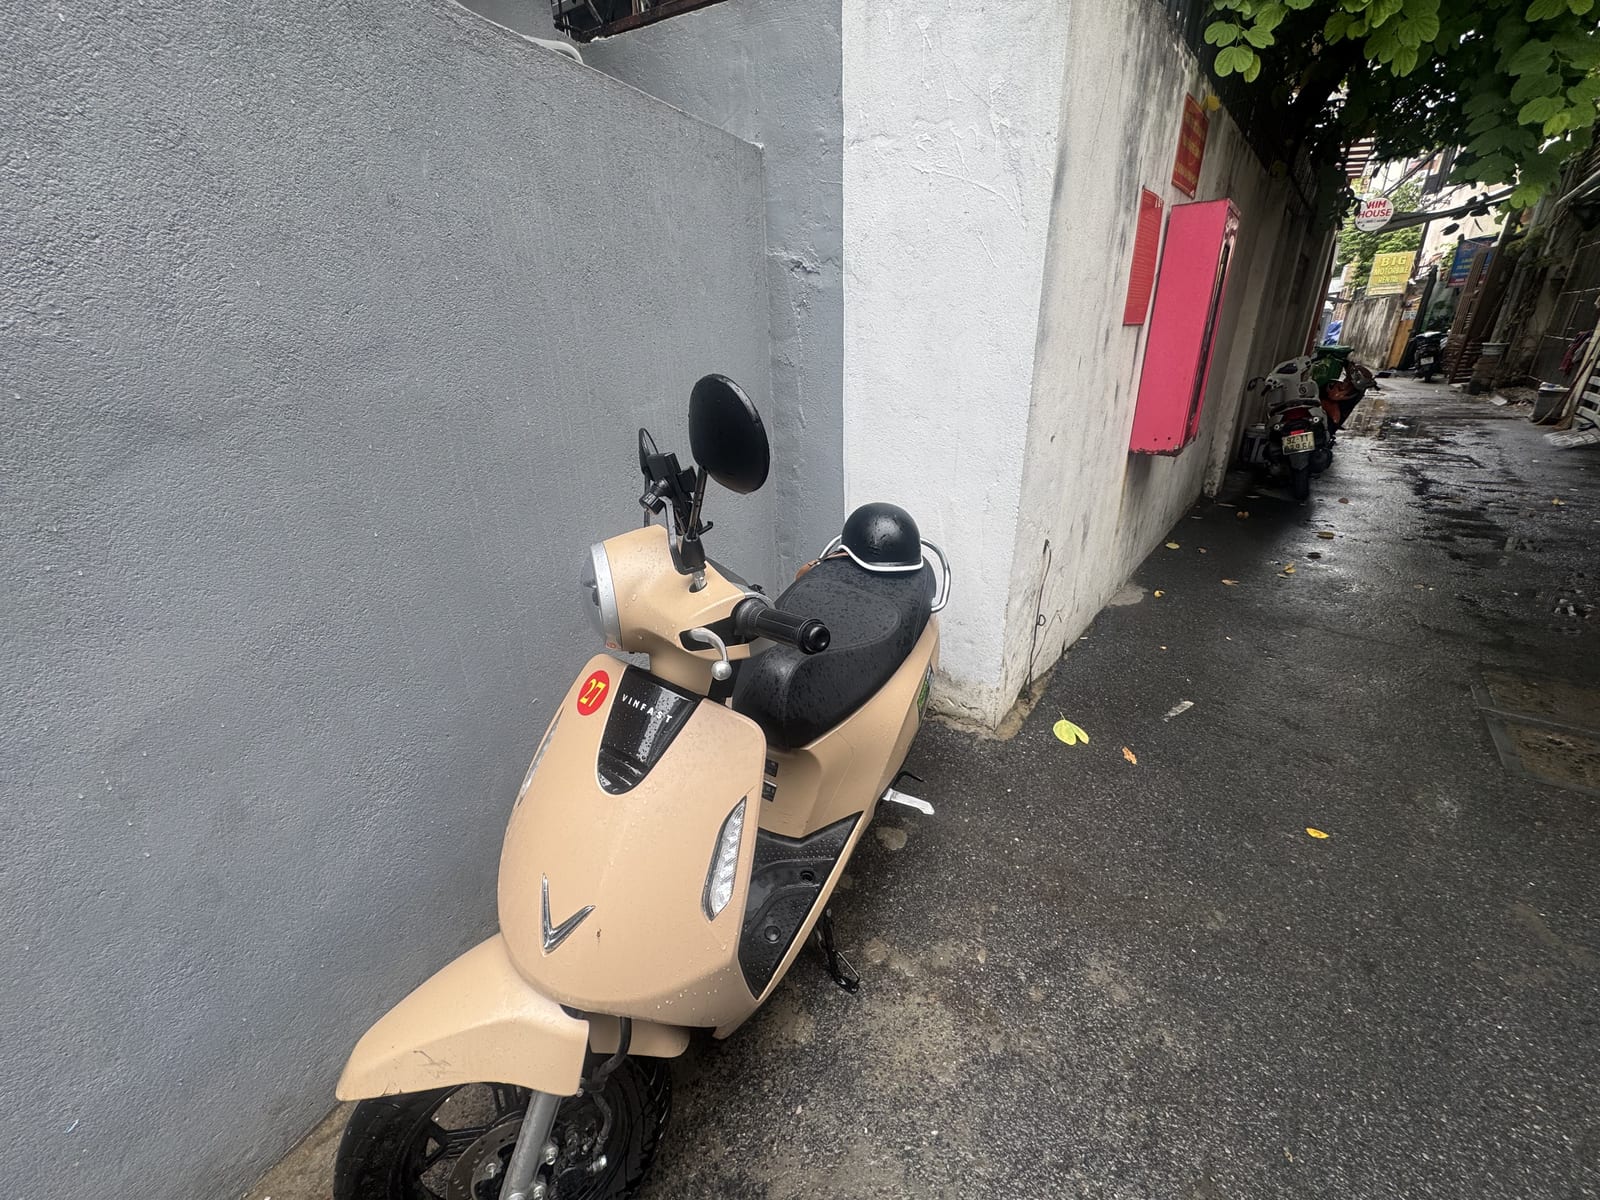
The electric motorbike I rent in Da Nang, helmet on the seat. Legal without a license, and always with a helmet
- Mental health, cancer and maternity are left out of Essential.
- Electronics theft is extra. With the add-on, up to $1,000 per device, but they knock off 2% for every month since you bought it and you have to report the theft to the police within 24 hours.
- The United States isn’t included unless you pay for the add-on.
- Sports above 4,500 meters are excluded, unless you have the adventure add-on.
What wins me over
- $2.24 a day for up to $250,000 of hospital cover
- You can buy it when you’re already traveling
- You pay every 4 weeks and stop when you get home
- One policy for every country on the trip
- A clear policy, written to be understood
Where it falls short
- With the 4-week plan, you almost always pay up front
- Electronics are extra and lose value fast
- No motorbike license, no cover
If I could ask them for just one thing, it would be about that first point: direct payment to the doctor shouldn’t depend on being admitted. In Asia a doctor’s visit is cheap, but tests at a private hospital in Bangkok or Bali are not, and having to put them on your own card is a headache that travel medical insurance for nomads should spare you. The annual plan partly fixes this, with the $150 card for minor visits, but the four-week plan, the one we use, doesn’t.
Why we chose it over the others
My partner compared other options before deciding. What she found is that a lot of insurance is designed for short trips, one or two weeks, and once you stretch it to a month or more the price shoots up.
SafetyWing is made for nomads, the kind who spend months in places like Chiang Mai, and you can see it in the numbers: for a month or longer, it came out cheaper for her, with good coverage.
Reputation mattered too. With travel medical insurance, the scary part isn’t the price, it’s running into the fine print the day you need it and having to pay the hospital out of your own pocket. That’s why a policy we can actually understand matters so much to us.
On top of that, the reviews are good: 4.3 out of 5 on Trustpilot, from more than 4,000 reviews. It isn’t one of those insurers that try to slip the fine print past you, and I like that.
I looked into it afterward, once she already had it. For what I need, three months moving around Asia and working, it’s the most complete option I’ve found for the price. If it weren’t, I’d buy a different one: I’m not tied to any brand, and I only write about products I use and like.
And here’s when I wouldn’t buy it: for a week or 10 days in Thailand or at the beach. This kind of travel medical insurance makes no sense for that, and it isn’t designed for it. SafetyWing makes sense when the trip gets longer, when you don’t know when you’re coming back or when you’re hopping from country to country.
SafetyWing discount code: how to use it
My code is DESCUBRIENDO. If you’re a new customer and buy Essential, it gives you 8 weeks of the electronics theft add-on, the one that covers your laptop, phone or camera if they get stolen.
There’s a trick to it: you don’t enter the code at checkout. It goes in before you create your account, and the box is hidden inside an illustration. Here’s how:
- Go to the Nomad Insurance page through this link.
- Look through the illustrations on the page for one of the pink cameras and click on it.
- Type DESCUBRIENDO and confirm it. A message will tell you your electronics cover is locked in for 8 weeks.
- Then create your account and buy the plan as usual.
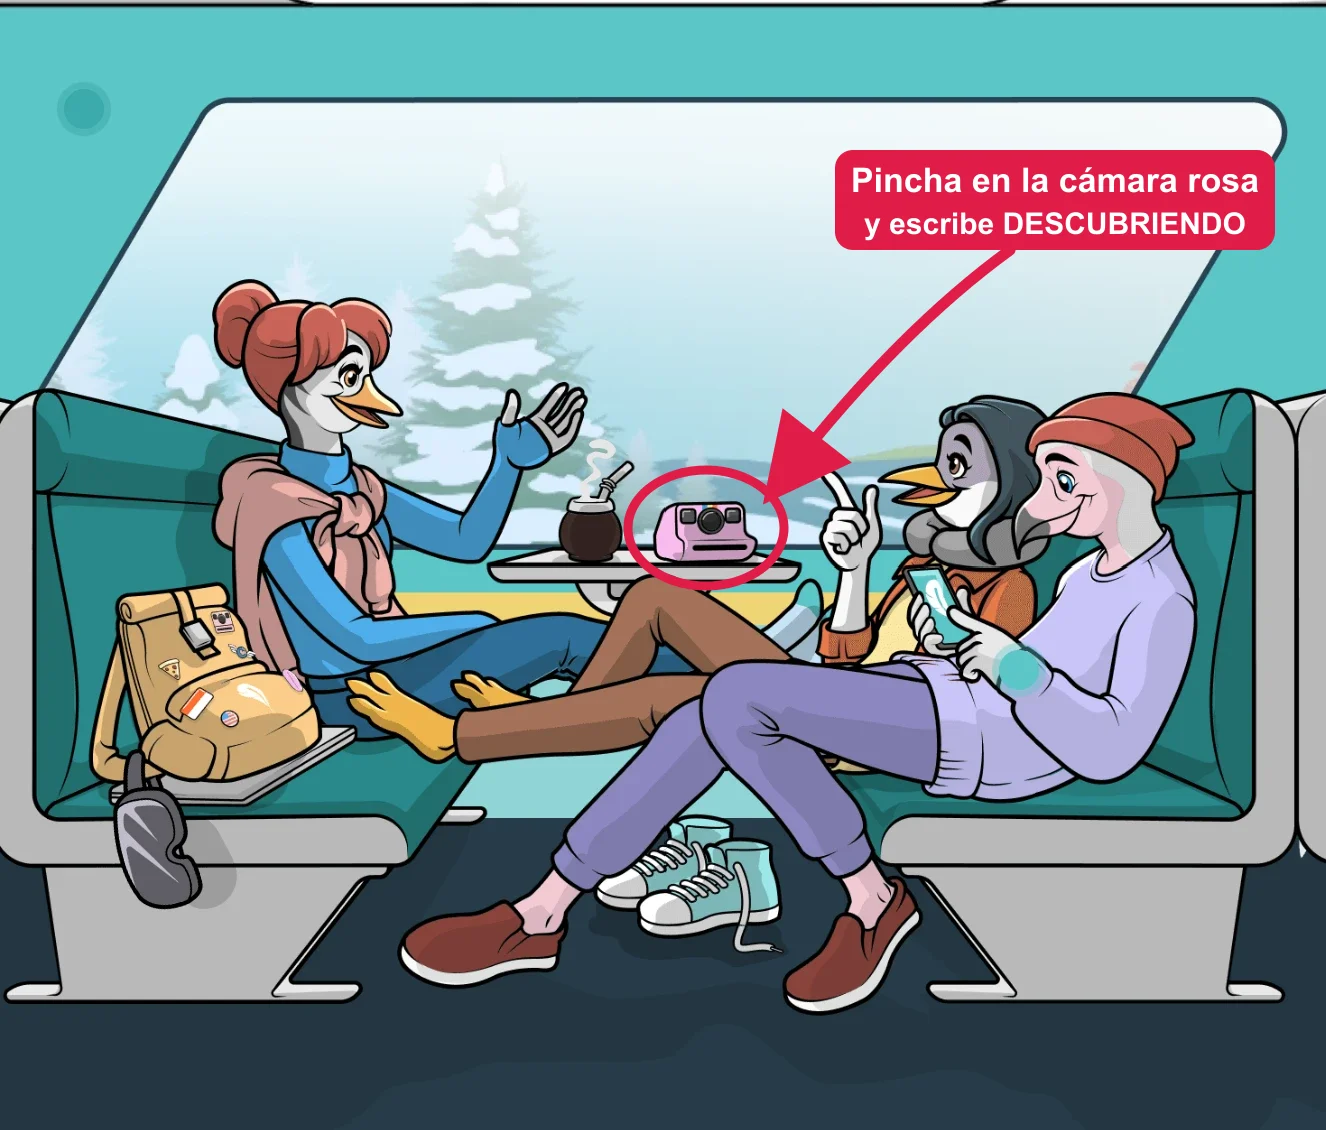
The pink camera where the code goes. Click it before you create your account
Go to SafetyWing and find the pink cameraWhat to do if something happens
We haven’t had to use it, so this isn’t my own experience: it’s what their policy says you have to do, laid out in order so you have it handy the day you need it.
- If you’re going to be admitted, let them know before you’re discharged. Use their assistance chat, which is open around the clock and, according to them, answers in 2 or 3 minutes. It’s the only way for them to pay the hospital directly.
- If it’s a doctor’s visit or an emergency without admission, you pay, with your own card or with the prepaid one if you have the annual plan or Complete. Keep the proof of payment.
- Ask for the medical report before you leave, with the diagnosis and the date your symptoms started. It’s much harder to get later.
- Ask for an itemized invoice, showing what each thing cost, not just a total.
- If you’re robbed, report it to the police and keep a copy of the report.
- File your claim from your SafetyWing dashboard, from their app or by email, no later than 60 days after your coverage period ends. According to them, it takes a minute or two in the app.
They say the money arrives within a few days. I haven’t been able to check that, and if I ever have to file a claim, I’ll tell you about it here, with dates.
If they turn down a claim, they have to explain why in writing, and you can appeal up to twice within the following six months.
Frequently asked questions about SafetyWing
Is there a discount code for SafetyWing?
Yes: with the code DESCUBRIENDO, new Essential customers get 8 free weeks of the electronics theft add-on. It doesn’t go in at checkout: you type it before creating your account, by clicking one of the pink cameras on the Nomad Insurance page.
Can I buy travel medical insurance after I’ve already left home?
With SafetyWing, yes. You can buy it before you leave or at any point during the trip. If you’re already abroad, coverage starts as soon as you get the email with your policy. If you buy it from home, it starts when you cross the border.
How much does SafetyWing cost per day?
Essential costs $62.72 every four weeks between the ages of 18 and 39, about $2.24 a day. If you pay for 364 days at once, it drops to $56.45 every four weeks. From age 40, it goes up by age bracket.
Can I pay month by month?
Yes, Essential is charged every four weeks and you can cancel whenever you like. If you cancel partway through a period, they refund the part you haven’t used, minus $25, as long as you haven’t claimed anything.
Does SafetyWing have a deductible?
Essential has no deductible: whatever they approve is reimbursed in full. The catch is that, in general, you pay up front and claim the money back afterward.
Does SafetyWing pay the hospital directly?
Only for hospital admissions outside the United States, and you have to let them know before you’re discharged so they can arrange it. For doctor visits and emergencies without admission, you pay and claim afterward, unless you have the annual plan or Complete, which come with a prepaid card loaded with $150 or $500 for minor doctor visits.
Does it cover me in Thailand, Vietnam and Indonesia?
Yes. It covers more than 180 countries under the same policy, so you can hop from country to country without changing anything. The United States is the exception: it comes as a paid add-on.
Does it cover a motorbike accident in Asia?
Only if you have a valid license for that bike, you’re wearing a helmet and you haven’t been drinking. Before renting one in Vietnam or Thailand, check what that country’s law says about the license you hold.
How do I protect my laptop and phone against theft?
With the electronics theft add-on: up to $1,000 per device and $3,000 per period. With the code DESCUBRIENDO, the first 8 weeks are free. They deduct 2% of the value for every month since you bought it, and they ask for the purchase receipt and a police report filed within 24 hours.
Does it cover non-urgent doctor visits?
Essential doesn’t cover checkups or routine care: it’s for new, unexpected problems. For that you need Complete, which is full health insurance.
So, is SafetyWing worth it in Asia?
For me, yes, if the trip is longer than a month. For $2.24 a day you get hospital, evacuation and luggage cover in every country you set foot in, and you can buy it when you’re already away and stop it when you get back.
It isn’t perfect. With the 4-week plan, you’ll almost always pay up front, electronics are extra and there’s no cover without a motorbike license. But it’s what we’ve chosen for our own trips, first her this summer and now both of us, and in January I’ll update this article with how it went.
I only write about things I use and like, and this is one of them.
Keep planning your trip
 Safety
A 10/10 review posted from my account that I never wrote, two days in bed after a tourist dinner, and the legal mess around motorbikes.
Read the guide Where to stay
Which area suits you depending on what you’re after, and why picking the wrong one means blowing your budget on taxis.
Read the guideShare this and decide together 💙